Commercial Truck Insurance for Australian Operators
Commercial truck insurance arranged by a broker who has actually managed trucks, not just written policies.
From a single prime mover to a fleet of a hundred, we structure cover around how your operation really runs, your values, your freight task, your contracts and where the risk actually sits.
Insurance From a Team With Industry Experience
Most commercial truck insurance is bought by filling in a form. You answer the insurer's questions about your trucks and your business, get a price, the policy is written and that is the end of it.
That works until you have ten, twenty or a hundred pieces of equipment and a total loss, where a truck is written off, lands on your desk. Then it matters whether your broker actually understands transport.
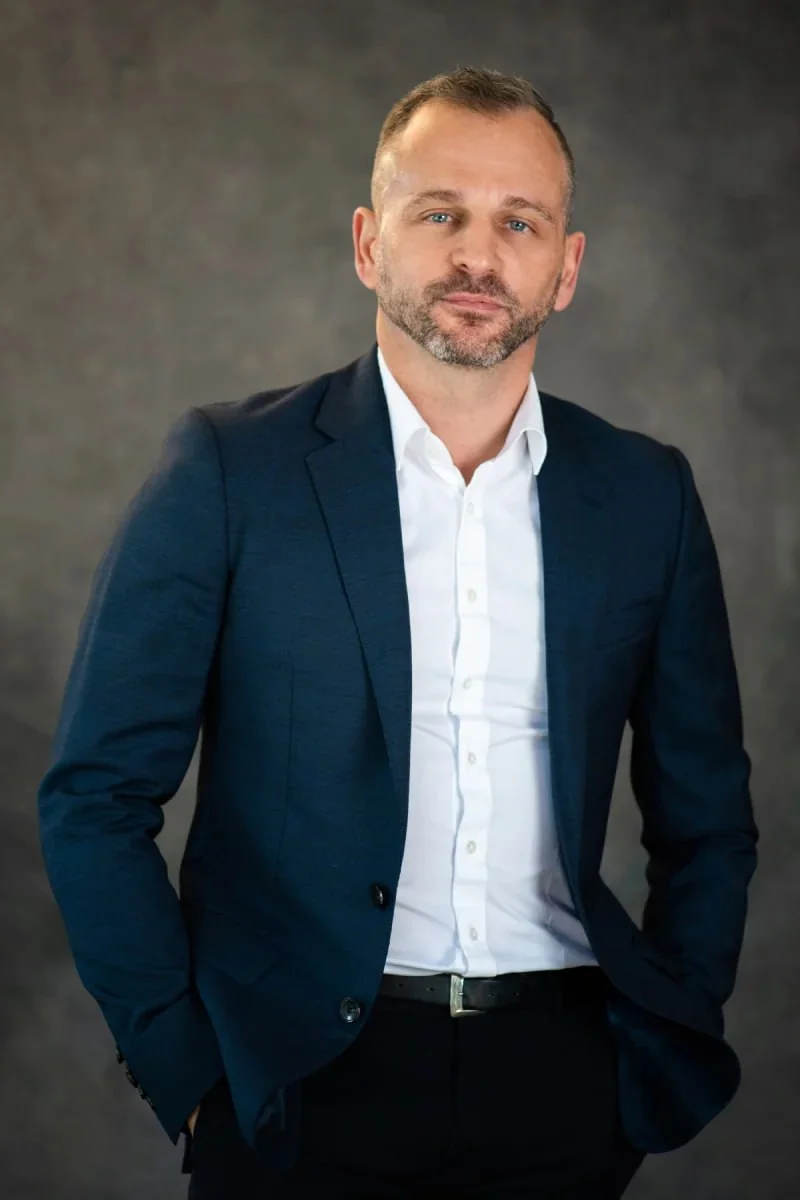
Before broking, Paul Cohalan managed heavy haulage for BHP across the Iron Ore operation, ran a section of the Roy Hill construction build and moved oversized resource equipment that had never been moved that way before. He has spent the ten years since then in insurance, and he works the same way with every client: learn how the business runs, earn their trust and explain the cover plainly.
Paul founded All Trucks Insurance, and every broker on the team works the same way. They all specialise in transport, so they know how your freight moves as well as what the policy says.
Get the Right Cover With Paul
“Everyone can fill out a form and write a policy. Understanding your values, your contracts and where the risk actually sits, that is a completely different game.”
Paul Cohalan
Founding Principal Broker
Call Paul on 1300 78 78 25Backed by Australia's Leading Heavy Vehicle Insurers
We place truck and transport business with the specialist underwriters that actually understand heavy vehicle risk, under a brokerage licence backed by Steadfast.

Who We Arrange Commercial Truck Insurance For
If it carries freight, tows a trailer or earns its money on the road, we can arrange cover for it. Every operation is different, so we set up the cover around the trucks you run, the work they do and the contracts you work under.

Owner-Operators
One-truck operators and one-man-band operations who still deserve a broker in their corner.
Small Fleets
Growing businesses running five to thirty trucks, trailers and assets under one program.
Large & Long-Haul Fleets
Fifty to a hundred-plus prime movers, trailers and equipment moving freight interstate.

Refrigerated Transport
Reefer operators carrying perishable and temperature-sensitive freight.

Tippers & Bulk Haulage
Tippers, drop decks, flat tops and tautliners hauling bulk and general freight.
Oversized & Over-Mass
Heavy haulage, oversized loads and over-mass movements with their own risk profile.

Civil & Construction
Civil operators running mixed fleets of trucks alongside plant and equipment.

Agriculture & Livestock
Rural transport, livestock carriers and agricultural freight operators.

Logistics & Warehousing
Logistics businesses, distribution and warehousing operations with vehicles in the mix.

Cranes & Lifting
Crane and lifting equipment, high-risk, specialised, and a space we actively place.

Plant & Equipment
Yellow goods, mobile plant and mining-grade equipment beyond the trucks.
Subcontractor Fleets
Operators running subcontractors who need their cover aligned to the head contract.
Don't See Your Operation Here?
Tell us what you run and how, and we will put together cover that fits.
What Your Cover Can Include
Most operators need more than one type of cover. These are the ones we arrange most often.

Comprehensive Motor & Physical Damage
Accident, fire, theft and storm damage to your prime movers, rigids and trailers, including the accessories fitted to them.

Third Party Property Damage
Cover for damage your trucks cause to other people's vehicles and property, which every operator on the road needs.

Public & Products Liability
Protection against claims for injury or damage arising from your business activities, including delivery and handling.

Marine Cargo & Goods in Transit
Cover for the freight you carry, from general cargo to the specialised and high-value loads that standard policies miss.

Trailer Cover & Trailer-in-Control
Trailers get swapped between trucks all the time. Cover for your own trailers and the ones you tow but don't own.

Downtime & Business Interruption
Most of your income comes in while the truck is moving. This cover helps replace it while a vehicle is off the road.

Plant, Equipment & Machinery
Cover for excavators, loaders and other mobile plant, plus machinery breakdown, for fleets that run more than trucks.

Personal Accident & Workers' Comp
Cover for your drivers and staff if they are hurt on the job, because without them none of the trucks move.
We also place occupational accident, non-trucking liability and ad-hoc endorsements as your operation changes.
The Gaps That Catch Operators Out
These are the things we see go wrong, the ones that turn a bad day into a financial hit the business cannot absorb.
Not Knowing Your Values
A truck can be worth half a million in accessories before it earns a dollar. If your declared values are out of date, you find out at claim time, when it is too late. We tell operators to check or get valuations done three to four months before renewal, not the week of.
Insuring the Truck, Forgetting the Trailer
Plenty of operators insure the prime mover and overlook the trailer, where a lot of the value and cargo sits. Trailers get detached and swapped, and a non-owned trailer in your control is still your exposure.
Underestimating Downtime
If a truck is off the road for weeks, that is revenue gone, not just a repair bill. Without business interruption or a replacement plan, the loss compounds while margins are already tight.
Subcontractors and Chain of Responsibility
Logistics and transport runs on subcontractors. Without aligning their cover, the principal's indemnity and the contractual obligations to your tier-one and tier-two contracts, the risk lands back on you.
Treating Insurance as Transactional
Anyone can fill out a form and write a policy. The value is in understanding your fleet, your history, your activities and your contracts, then putting the best version of your risk to the market.
Set-and-Forget at the Wrong Scale
Going from five vehicles to twenty makes you a different business with a different risk profile. Cover that fit last year does not automatically fit the operation you have become.
A Real Claim, Handled the Right Way
When you make a claim, we deal with the insurer for you and push for the best result. This is how that went on one claim we handled, with the client's details changed and the figures rounded.
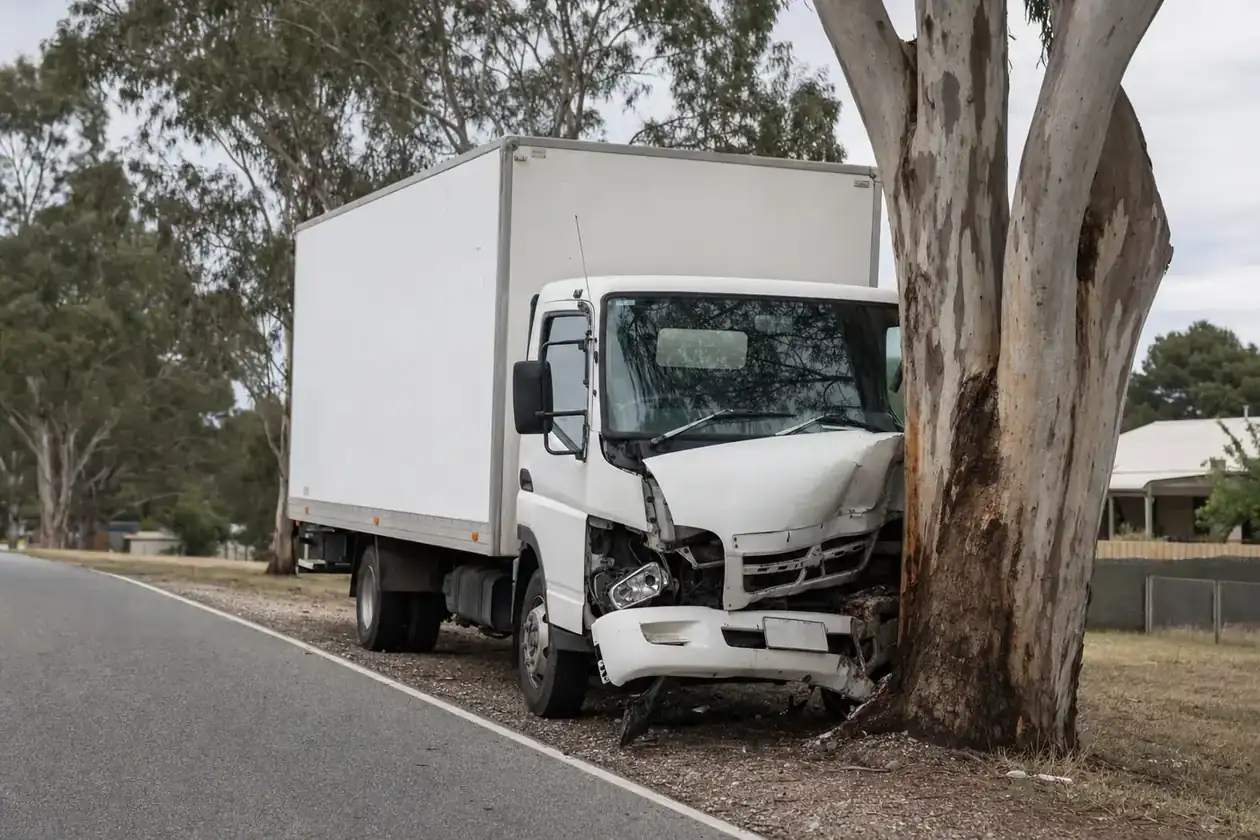
A Delivery Run, a Gum Tree, and a Claim That Didn't Blow Out
A young driver on a local delivery clipped a gum tree at low speed in a rigid truck and tore up the whole front end. Nobody was hurt, but it left a real repair bill, and a client who had already had a couple of claims and could not afford his premium climbing again.
Left on autopilot, the insurer defaults to a brand-new repair. It is the most expensive path, and the one that hits hardest at renewal.
Instead we went back to the insurer's own repair manager and worked out a smarter outcome, a sound second-hand replacement that does exactly the same job for the truck. The claim cost stayed contained, the truck got back on the road earning, and the client's renewal was protected.
We got that result because we know the insurer and the repair side, and we picked up the phone for our client.
Illustrative example based on a real claim handled by our team. Client details anonymised and figures approximate.
How We Arrange Your Cover
A straightforward process built around understanding your operation before we talk price.
1. Understand Your Operation
Your trucks, trailers, freight task, contracts, history and how the business actually runs.
2. Build the Risk Profile
We find the gaps, work your values and put the best, most accurate version of your risk to the market.
3. Arrange the Right Cover
We place the program with the specialist insurers who understand heavy vehicle risk, not generalists guessing at it.
4. Renewals, Claims & Ongoing
We manage renewals, fight the claims and handle the mid-term changes as your fleet grows and shifts.
What Shapes Your Commercial Truck Insurance Premium
There is no flat rate. Your premium depends on how your operation runs, and a broker who understands it can explain your business to the insurer in the best light.
We do not quote a number off a website. We build your risk profile properly and put it to the market, request a custom quote and we will work it through with you.
- Fleet size and the declared values of your vehicles
- Vehicle types, prime movers, rigids, trailers, reefer, tippers, plant
- Your freight task and operating radius
- Claims history across the fleet
- Driver experience and how you onboard them
- Subcontractor exposure and contractual obligations
- Maintenance, in-house or outsourced, and how it is run
- Where your fleet is based and garaged overnight
Related Cover
Most operators need more than one policy. Here are the covers they usually add.
Get Your Commercial Truck Insurance Sorted
Whether you run one prime mover or a hundred, you need commercial truck insurance arranged by a broker who understands how you operate and who deals with the insurer for you when you claim.
Send us a list of your trucks and trailers, what you carry and where you run, and we will come back to you with a quote.
Commercial Truck Insurance FAQs
Commercial truck insurance is usually a set of covers. It can include comprehensive motor and physical damage, third party property damage, public and products liability, cover for the freight you carry (called marine cargo or goods in transit), trailer cover, downtime and business interruption, personal accident and workers' compensation. The right mix depends on your operation, your freight task and the contracts you run under.
For most heavy vehicle operators, motor and public liability are the two must-haves. Motor protects the vehicles; public liability protects you against claims for injury or property damage arising from your business activities, including delivery and handling.
Trailers carry a lot of value and are constantly detached and swapped between trucks. Trailer-in-control cover protects you against liability for damage to a non-owned trailer while it is in your possession and used for work, even if it is not registered in your name.
One truck is rated on its own, priced as a percentage of what it is worth. Somewhere around sixteen units most insurers will move you onto a fleet schedule and a unit rate instead, though there is no hard number.
The bigger change is that your claims are then read as one loss ratio rather than separately, so the training, maintenance and onboarding you already do starts moving the premium.
Fleet size and declared values, vehicle types, your freight task and operating radius, claims history, driver experience, how much work you give to subcontractors and how your maintenance is run all move the number. A broker who understands transport can explain your business to the insurer accurately and in the best light.
Yes. We work across reefer, tippers, drop decks, flat tops, tautliners, oversized and over-mass movements, civil and construction fleets, cranes and lifting, and mixed fleets running plant and equipment alongside trucks.
We place marine cargo and goods-in-transit cover for the freight you carry, including specialised and high-value loads. This is often where generalist policies fall short for transport operators.
Downtime is lost revenue, not just a repair bill, because most of a transport operator's income happens when the vehicle is moving. Depending on the program, business interruption, increased cost of working or a replacement vehicle can help keep the revenue coming while the claim is managed.
Once you have real fleet, real values and real contracts, you need an advisor, not a transaction desk. A specialist broker structures your cover, works your values, holds the insurers to account and fights your claims, like the total loss we pushed from a 48 per cent offer up to the full insured value.
We place business with Australia's specialist heavy vehicle insurers, including NTI, Global Transport (Allianz), HMIA, Zurich, QBE and UAA, under a brokerage licence backed by Steadfast.
Compliance Disclaimer: This information is general in nature and does not take into account your objectives, financial situation or needs. Please consider the relevant Product Disclosure Statement (PDS) before making any decision.