Semi Trailer Insurance for Australian Transport Operators
Specialist cover for the trailers that carry your freight and a lot of your value, arranged by brokers who understand transport.
Semi-trailers, drop decks, flat tops, curtainsiders, reefer and tipper trailers, dollies and low loaders, whether you own them, lease them or tow someone else's.
The Half of Your Rig Operators Often Underinsure
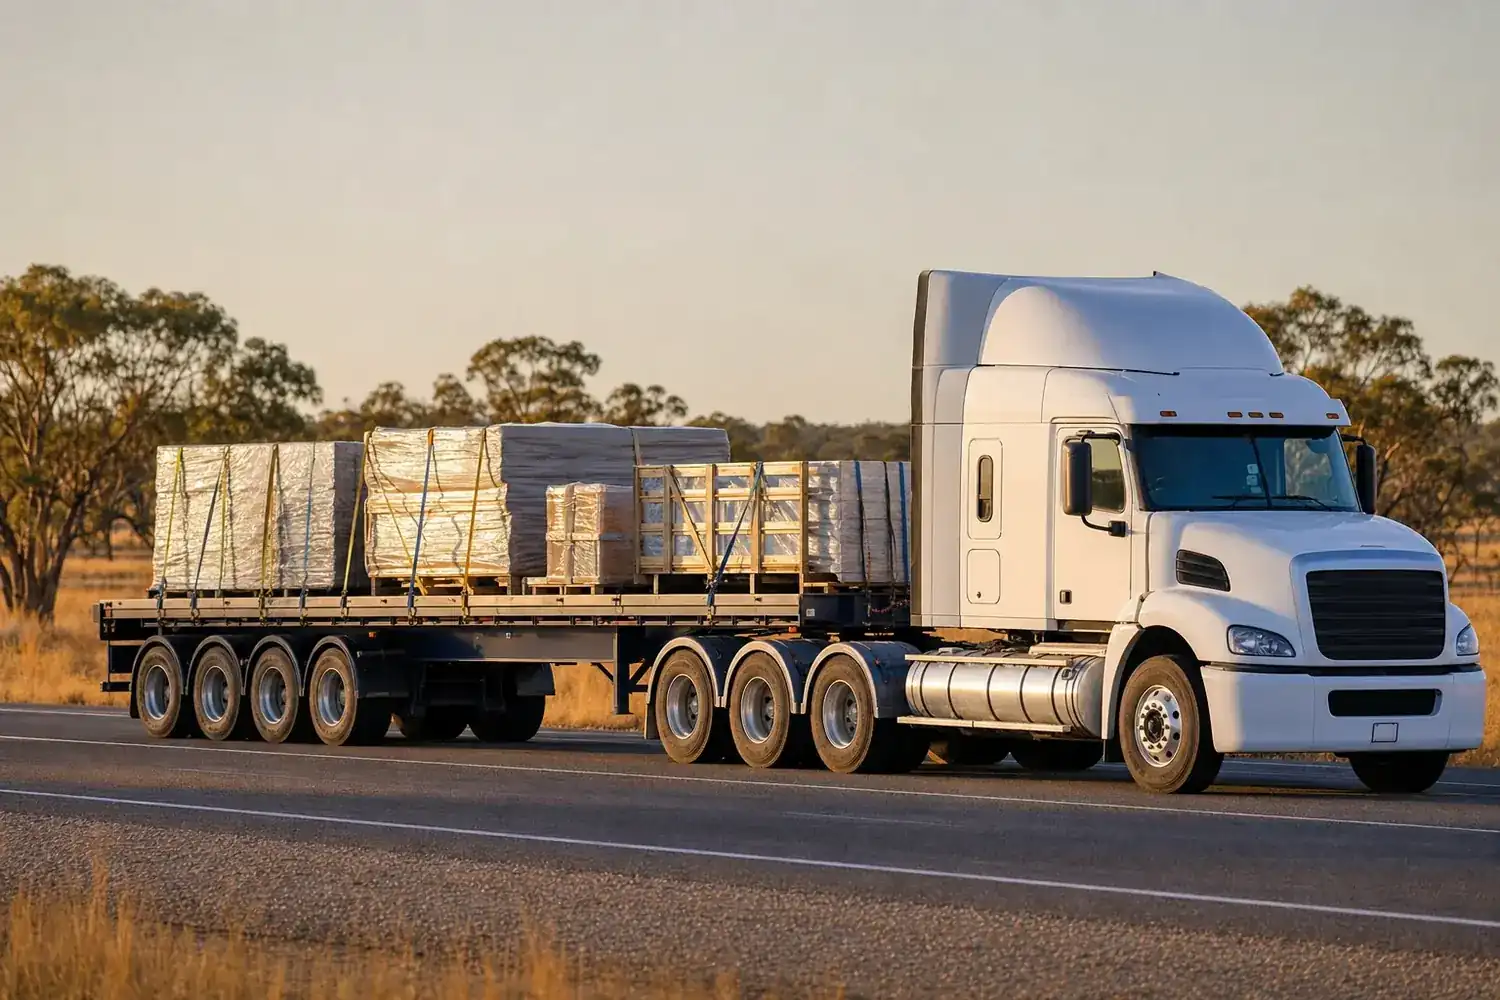
Plenty of operators insure the prime mover properly and leave the trailer as an afterthought. A loaded drop deck, a refrigerated trailer or a curtainsider full of freight can carry more value and more risk than the truck pulling it.
We have managed heavy haulage and run the gear, so we set up semi trailer insurance around how your freight task works. That starts with current declared values, the amount you tell the insurer each trailer is worth, and the accessories that add up.
Then there is the liability you take on the moment someone else's trailer hooks onto your truck, which is what trailer-in-control cover is for.
Paul Cohalan founded All Trucks Insurance, and every broker on the team specialises in transport.
Get the Right Semi Trailer Cover With Paul
“The trailer carries the freight and a lot of the value, but it is the first thing operators underinsure. Get the values and the trailer-in-control right and you have closed the gap most policies leave open.”
Paul Cohalan
Founding Principal Broker
Call Paul on 1300 78 78 25Backed by Australia's Leading Heavy Vehicle Insurers
We arrange trailer and transport cover with the insurers that write heavy vehicles, under a brokerage licence backed by Steadfast.

Trailer-focused advice
We advise operators who run semis, drop decks, reefers and tippers, as well as the trucks pulling them.
Values & risk reviews
We help keep your declared trailer values and accessories up to date, so the cover matches what you run.
Claims fought for you
When a trailer or its freight is damaged, we deal with the insurer for you and push for a fair result.
Australia-wide cover
Your cover follows your trailers around the country, including trailers you don't own that are hooked to your truck.
Semi Trailer Insurance for the Trailers You Run
If it gets towed behind a prime mover or a rigid and earns its money on the road, we can arrange cover for it. Each operation is set up on its own, around the trailers you run and what they carry.
Semi-Trailers
Each semi on its own declared value, whichever prime mover pulls it.
B-Doubles & Road Trains
Every trailer in the combination listed, so none is missed at claim time.
Flat Tops & Drop Decks
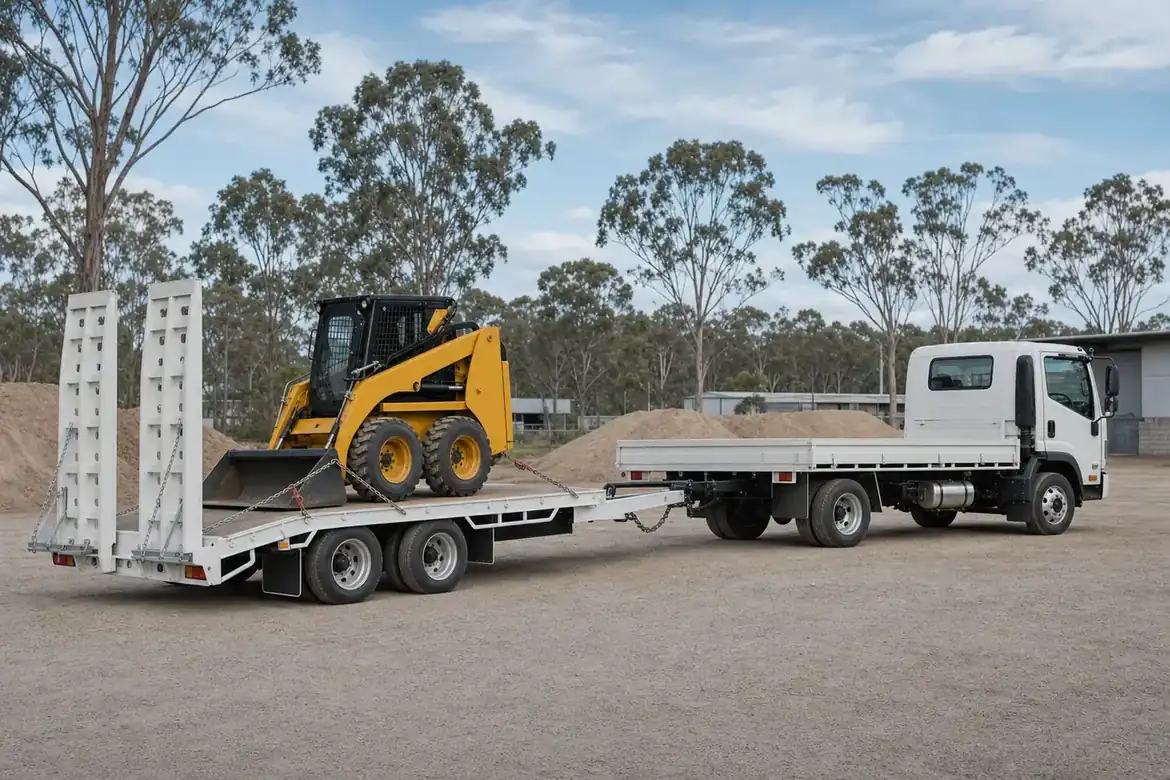
Decks, ramps and low loaders valued with the gear fitted to them.
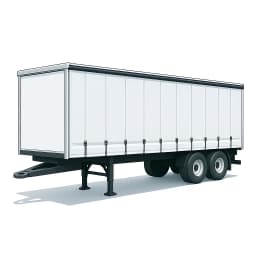
Curtainsiders & Tautliners
Curtains and load restraint gear declared with the trailer.
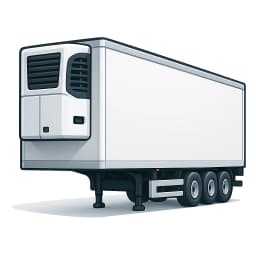
Refrigerated Trailers
The reefer unit declared with the trailer, not left off.
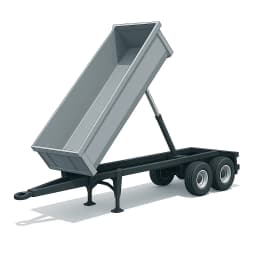
Tippers & Bulk Trailers
End and side tippers moving spoil, aggregate and grain.
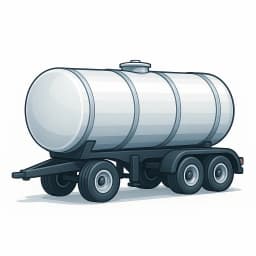
Tankers
Liquid, fuel and dry-bulk tankers, each with its own risks.
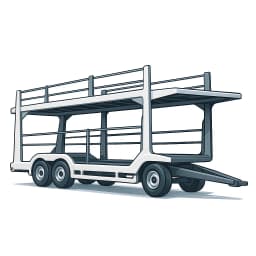
Car Carriers & Specialised
Car carriers, livestock crates, dog trailers and more.
Don't See Your Trailer Here?
Tell us what you tow and what it carries, and we'll set up the cover.
Trailer-in-Control & Non-Owned Trailer Liability
The moment you hook a trailer that is not registered in your name onto your truck, you take on responsibility for it, and most standard motor policies do not cover that trailer.
Trailers are unhooked, swapped between trucks and sub-hired (hired in from another operator) all day. A trailer sitting in your yard or being towed under your contract is your risk, even though your name is not on the rego.
Trailer-in-control cover protects you against liability for loss or damage to a trailer you don't own while it is in your possession and used for your work. If you sub-hire or move other people's trailers, it can stop a damaged trailer becoming a bill you pay yourself.
Non-Owned Trailers
Liability for trailers in your possession that you don't own.
Follows the Trailer
Cover that moves with the trailer between prime movers.
Sub-Hire & Contract
Cover for sub-hired and contracted trailer movements.
In Your Yard
Trailers unhooked, parked or stored on your site.
What Your Semi Trailer Insurance Can Include
Most trailers need more than one type of cover. These are the ones we arrange most often.
Accidental Damage, Fire & Theft
Damage to your trailers from collision, rollover, fire, theft and storms, wherever they are working or parked.
Trailer-in-Control & Non-Owned
Liability for trailers you don't own or have hired in, while they are hooked to your truck or in your care.
Goods in Transit & Cargo
Cover for the freight on the trailer, from general cargo to the specialised loads standard policies miss.
Refrigeration & Accessories
The reefer unit, curtains, ramps, gates and load restraint gear that add real value to a working trailer.
Third Party Property Damage
Cover for damage your trailer causes to other people's vehicles and property, which every unit on the road needs.
Public & Products Liability
Cover for injury or damage claims that come from loading, unloading, restraining and moving freight.
Downtime & Replacement
When a trailer is off the road after an incident, the freight still has to move. This cover helps pay for a replacement.
Trailer Fleets Insured Together
Two trailers or two hundred, we arrange them together and keep the declared values current as you add units.
We also arrange loss of use cover (for income lost while a trailer can't work), recovery costs (getting a damaged trailer towed or lifted off the road) and one-off policy changes as your trailer fleet changes.
The Gaps That Catch Trailer Owners Out
These are the trailer mistakes we see turn a routine incident into a bill the business has to pay itself.
Insuring the Truck, Forgetting the Trailer
The prime mover gets the attention and the trailer gets an old value or no separate cover at all, even though a loaded trailer can be worth more than the truck. We value the trailer on its own.
No Trailer-in-Control Cover
Operators tow trailers they don't own or have hired in every day, and assume someone else's policy covers them. When one is damaged in your care, that assumption becomes your bill.
Undervalued Reefer Units and Accessories
A refrigeration unit, tautliner curtains and load restraint gear add tens of thousands before a trailer carries a single pallet. If they are not declared, they are not paid at claim time.
Forgetting the Freight on the Trailer
Damage to the trailer and damage to the cargo on it are two different covers. Without goods in transit cover, a damaged load is an uninsured loss for you and an unhappy customer.
Downtime on a Single Earning Unit
If a specialised trailer is off the road for weeks, the work it was built for stops earning. Without a replacement or downtime plan, the loss grows while the work goes elsewhere.
Set-and-Forget as the Fleet Grows
Adding trailers, changing freight tasks or starting to hire trailers in changes your risk. Cover that fitted a two-trailer operation won't automatically fit the fleet you run now.
How Trailers Step Up Through a Working Fleet
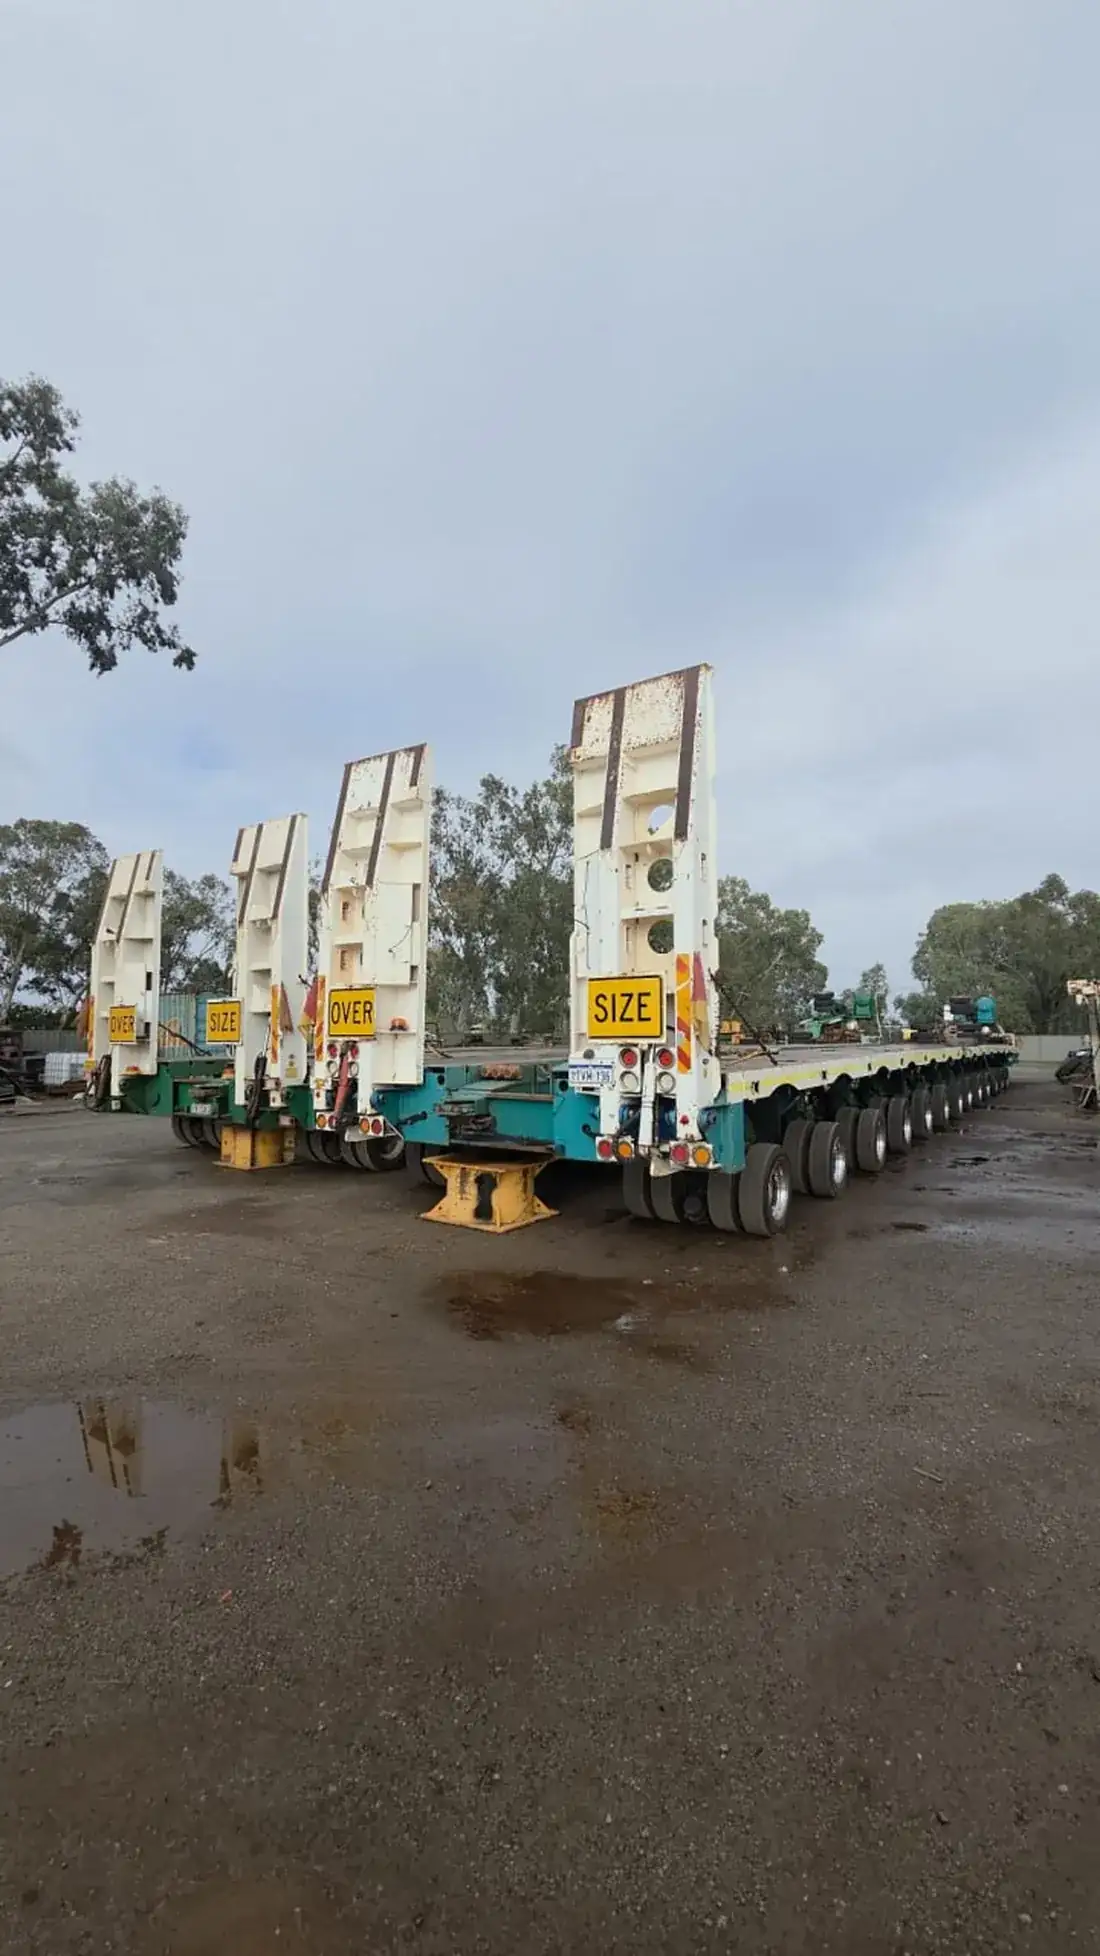
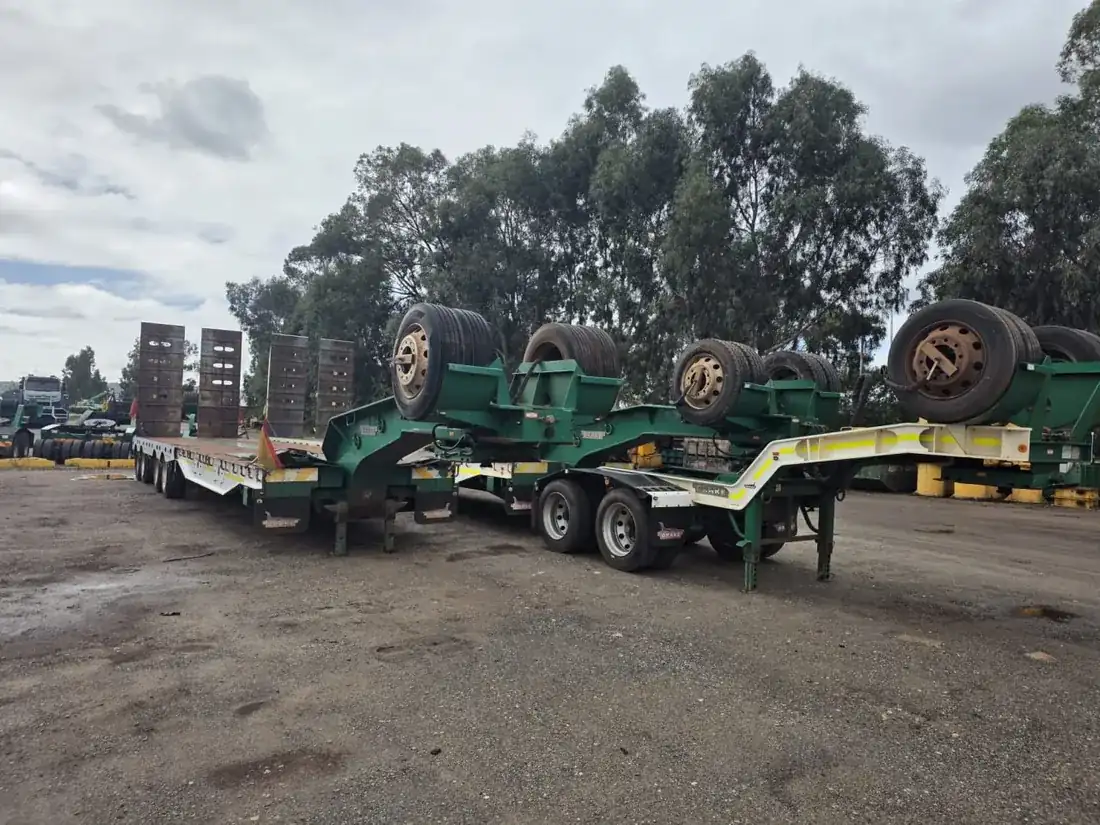
Most fleets start with a flat top and step up from there, sometimes as far as a hundred-tonne float. Each step changes the value on the deck, the way the load behaves and the cover the trailer needs. How a trailer is built, loaded and maintained decides a lot of what it costs to insure.
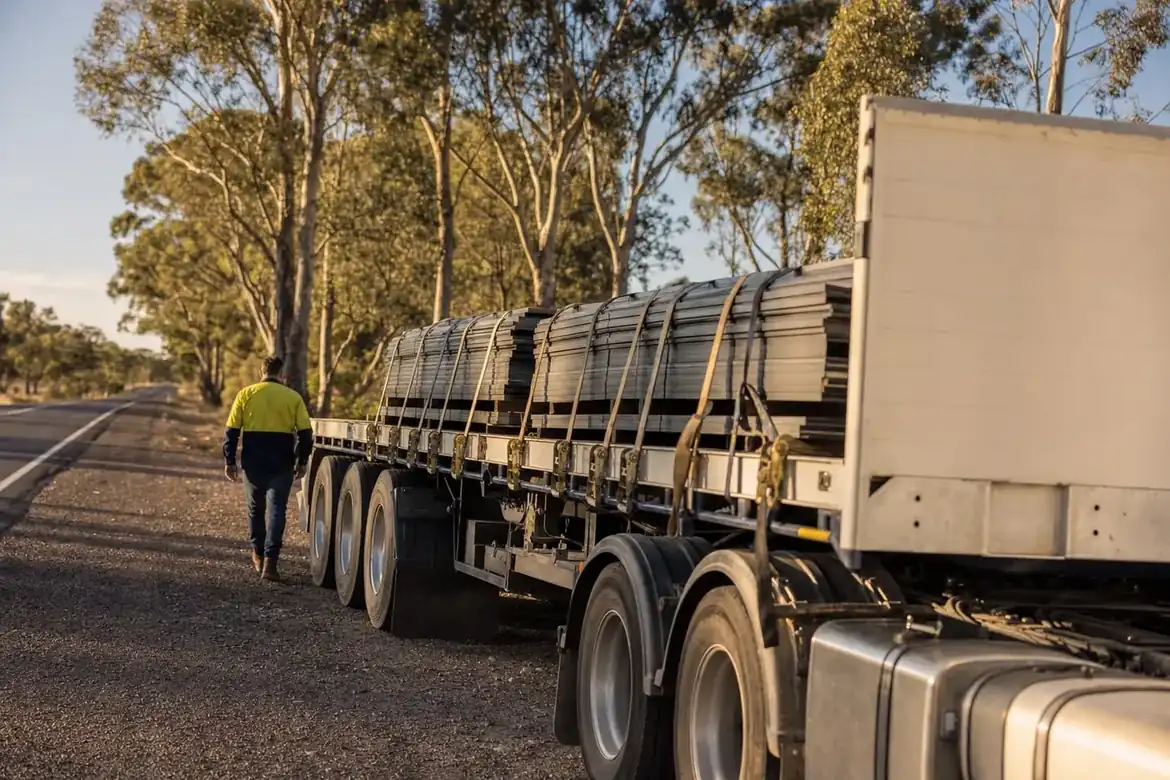
Flat Tops & General Freight
The flat top, or general plate trailer, moves from job to job, which is part of its value. It is usually the first trailer on the schedule.
Drop Decks & Ramps
A drop deck steps the front down so the load sits lower and stays under height limits, and ramps let it carry plant around town. That lower deck is what keeps the load legal.
Floats & Heavy Floats
Step up to floats, 2x4, 4x4, 4x8 and the 50, 75 and 100-tonne floats, and you are putting machines on the deck. Weight distribution and the float's rating start to matter as much as deck space.
Tautliners, Reefers & Specialised
Enclosed tautliners, refrigerated reefers, livestock crates and purpose-built blade trailers each carry their own value and their own risks. We look at each one on its own when we set the value.
Heavy trailers commonly run anywhere from around $30,000 to well over $200,000 once you count the deck, the ramps, the reefer unit and the accessories, which is why getting the declared values right before renewal matters so much.
What Owning the Right Trailer Really Involves
Watch Your Height and Width
Go over width and you are into oversize and over-width work, with permits, pilots and a different risk again. Tell us before you take that work on, because the cover may need to change.
Three Trailers, One Conveyance
Hook up a triple road train and the three trailers run as one conveyance: one trip, one moving risk. We check how your policy treats that combination before you need to claim.
Weight Distribution and Dollies
A 50-tonne float will not always take a full 50 tonnes. You load the weight forward and run a dolly up front to balance the combination. The cover should match how the gear is really loaded.
How We Arrange Your Semi Trailer Insurance
We start with how your trailers earn their money, and only then talk price.
1. Understand Your Trailers
Type, make, model, year and value of each unit, its accessories, whether it is custom built, who owns it and what it carries.
2. Get the Details Right
We bring your declared values up to date, find any trailer-in-control or goods in transit gaps, and explain it all to insurers.
3. Arrange the Right Cover
We take your trailers to the specialist insurers who understand heavy vehicle and trailer risk, and lay out the options for you.
4. Renewals, Claims & Ongoing
We keep values current as you add units, deal with the insurer on your claims and handle the changes as your trailer fleet grows.
What Shapes Your Semi Trailer Insurance Premium
There is no flat rate. Your premium depends on the trailers, their values and the freight task, and a broker who understands it can explain your business to the insurer in the best light.
We don't quote a number off a website. We work through your trailers, values and freight first, then take them to the insurers. Ask for a quote and we will go through it with you.
- Trailer types and how many you run
- Declared values, including reefer units and accessories
- Whether you tow owned, leased, non-owned or sub-hired trailers
- The freight task and how far you run
- Claims history across the fleet
- Load restraint, maintenance and where trailers are stored
- Goods in transit and the value of the freight you carry
- The age, make and condition of each trailer
Related Cover
Most operators need more than one policy. Here are the covers they usually add.
Get Your Semi Trailer Insurance Sorted
Whether you run two trailers or a fleet of them, you need semi trailer insurance arranged by a broker who understands your freight task and what your trailers are really worth.
Send us a list of your trailers, what they carry and where you run, and we will come back to you with a quote.
Semi Trailer Insurance FAQs
Semi trailer insurance is usually a set of covers.
It can include accidental damage, fire and theft to the trailer, trailer-in-control and non-owned trailer liability, cover for the freight you carry (goods in transit or cargo), refrigeration units and accessories, third party property damage, public and products liability, and downtime or replacement cover. The right mix depends on your trailer types and freight task.
Not necessarily. Trailers can go on the same policy as your prime movers, but each one needs its own declared value, and trailers you don't own need trailer-in-control cover. A loaded trailer can carry more value and more risk than the truck towing it.
Trailer-in-control cover protects you against liability for loss or damage to a trailer you don't own while it is hooked to your truck or in your care for work. That applies even though it is not registered in your name. Operators who tow sub-hired or contracted trailers need it.
Yes. Trailers you don't own or have hired in are where operators most often get caught out. We set up cover so a trailer in your care is protected whoever's name is on the registration.
There is no flat rate. Premiums depend on the trailer values, the freight you carry, your claims history, load restraint and storage, and whether you run owned or non-owned units. We work through those details and take them to the insurers rather than quoting a number off a website, so ask us for a quote.
Yes. We arrange cover for reefer trailers and their refrigeration units, end and side tippers, bulk and grain trailers, flat tops, drop decks, curtainsiders, tankers, car carriers, livestock crates and dog trailers, each with its own risks.
Damage to the trailer and cover for the freight on it are two separate things. We arrange cover for the load, called goods in transit or marine cargo, so a damaged consignment is not an uninsured loss for you and your customer.
A specialised trailer off the road means the work it does stops earning. Depending on the policy, downtime, replacement or loss of use cover can help keep the work moving while the claim is sorted out.
Yes. Whether you run two trailers or two hundred, we arrange them together with declared values that stay current as you add and retire units.
We arrange semi trailer insurance with the insurers that write heavy vehicles in Australia, including NTI, Global Transport (Allianz), HMIA, Zurich, QBE and UAA, under a brokerage licence backed by Steadfast.
Underinsurance is one of the most common traps with trailers.
We help you build an asset register, a spreadsheet listing the make, model, year and type of each trailer and whether it is custom built. Then we confirm current values, including ramps, reefer units and accessories, a few months before renewal, so the declared value matches what the trailer is worth when you claim.
Claims can affect your renewal, which is why how a claim is handled matters. A specialist broker works the claim with the insurer, including the repair plan and how it is settled, to keep the cost down and limit the effect on your next premium.
Compliance Disclaimer: This information is general in nature and does not take into account your objectives, financial situation or needs. Please consider the relevant Product Disclosure Statement (PDS) before making any decision.